

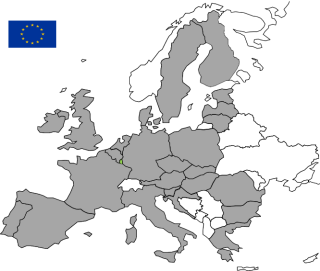
The European Union (EU) is composed of 27 Member States: Germany, Austria, Belgium, Bulgaria, Cyprus, Croatia, Denmark, Spain, Estonia, Finland, France, Greece, Hungary, Ireland, Italy, Latvia, Lithuania, Luxembourg, Malta, the Netherlands, Poland, Portugal, Romania, Slovenia, Slovakia, Sweden, the Czech Republic.
Since 1 January 2021, the United Kingdom has been a third territory.
Northern Ireland benefits from special arrangements provided for by the agreements concluded between the European Union and the United Kingdom. For trading goods, certain specific rules continue to apply.
Some national territories of these Member States are not part of the European Union.
For example: French Polynesia is an overseas collectivity that is not part of the European Union.
A detailed table of the territories concerned is available on the website of the European Commission.
The EU constitutes a European single market allowing the free movement of goods. This fundamental principle is based, in particular, on the existence of a Customs Union between the Member States and on the definition of an EU fiscal territory. However, the movement of goods that are subjected to excise duties within the excise territory is regulated.
The principle of the free circulation of goods is moreover subject to other restrictions imposed by law, concerning in particular:
- money, stocks and securities;
- automobiles and motorcycles;
- pets;
- guns, ammunition and narcotics;
- protected species of animals and plants.
As an EU Member State, Luxembourg benefits from the Customs Union and forms part of the EU fiscal territory and excise territory. Trade in goods involving Luxembourg territory benefits from the rules applicable within those territories.
1. The customs territory of the EU
Within the Customs Union, the 27 Member States of the EU form a single customs territory.
This means:
- No customs duty is applied on Union goods moving between Member States;
- Common rates of customs duty are applied when non-Union goods are imported into the EU;
- Member States apply common customs legislation established by the European institutions.
Other common rules established by the European institutions which must also be taken into account for customs purposes concern:
- preferential origin agreements;
- Sanitary, phytosanitary, environmental and food safety controls;
- common agricultural and fisheries policies;
- Protection of the EU’s economic interests through commercial policy measures.
Note: customs unions also exist between the EU and certain countries which are not members of the EU.
For example: a Customs Union exists between the EU and Türkiye concerning industrial products (excluding iron and steel products).
A detailed table of the territories that are part of the European Customs Union is available on the European Commission’s website.
2. The fiscal territory of the EU
Subject to certain exceptions, the territories of the Member States form the fiscal territory of the EU. Trade in Union goods taking place within this fiscal territory constitutes intra-Community trade.
Union goods move freely within the fiscal territory:
- they are not subject to customs declarations formalities or customs controls;
- they are subject to the harmonised rules on intra-community VAT and the applicable statistical obligations.
Non-Union goods that are placed in a suspensive customs procedure may generally benefit from a suspensive VAT arrangement.
Note: certain territories are excluded from the fiscal territory, while in some cases it is extended to countries which are not members of the EU.
Example: the French overseas departments and regions (Guadeloupe, Martinique, French Guiana, Réunion and Mayotte) form part of the customs territory of the Union but do not form part of the fiscal territory of the European Union.
A consignment of bananas originating in Martinique and delivered to Luxembourg must be declared to customs as an import. However, no customs duty will be payable because Martinique forms part of the customs territory of the Union.
Example: Monaco is not an EU Member State but forms part of the Customs Union and the EU fiscal territory. A sale of apple juice to a customer in Monaco must therefore follow the rules applicable to intra-Community VAT.
A detailed table of the territories concerned is available on the European Commission’s website.
The entire territory of Luxembourg forms part of the EU fiscal territory.
3. The excise territory of the EU
Subject to certain exceptions, the territories of the Member States included in the fiscal territory form the excise territory of the EU. The importation, production, movement and consumption of goods subject to excise duties within this excise territory must comply with the applicable excise rules.
Note: certain territories are excluded from the excise territory, while in some cases it is extended to countries which are not members of the EU.
Example: the Spanish Canary Islands form part of the EU and the Customs Union but do not form part of the EU fiscal or excise territory. A sale of wine to a customer in the Canary Islands must therefore follow the rules applicable to the export of goods subject to excise duties.
Example: San Marino is not a member of the European Union and does not form part of the Union’s fiscal territory. However, for excise purposes, movements of products subject to excise duty between EU Member States and San Marino are subject to specific rules and, in certain situations, are treated in a manner similar to intra-Community movements of excise goods. A sale of cider to a customer in San Marino must therefore comply with the specific rules applicable to such movements.
A detailed table of the territories concerned is available on the European Commission’s website.